RSS

News articles of '2018' 'April'

Stay up to date with gold, silver and platinum news, market developments and bullion insights.
Explore our latest articles or browse the archives to revisit the events that have shaped precious metal markets over the years.

Gold Mining Output 20 in Q1 at No. 1 Barrick But Rising Costs Lag Price

GOLD MINING shares rose as the broader stock market rallied Tuesday while the rise in US bond yields paused with 10-year rates just shy of 3%.

Gold bullion prices bounced $5 per ounce from yesterday’s 2-week low, touching $1328 as London opened for business.

That left gold little changed around last Friday’s finish in non-US currency terms as the Dollar joined bond yields and paused its rise of the last week on the FX market.

Silver and platinum kept all of Monday’s 2.7% and 1.0% drops respectively, trading back at $16.65 and $918 per ounce.

Palladium also failed to bounce after sinking over 6% yesterday amid reports that Washington may ease US sanctions over the metal against its No.1 miner, Russia.

The FTSE Gold Mines index meantime edged higher after the world’s largest stockmarket-listed gold miner reported a 5% rise in first-quarter earnings despite a 20% drop in gold ounces mined.

Announcing suspension of a “prefeasibility study” on the Andes mountain project at Pascua-Lama – expected to produce 125 tonnes over its first 5 years but shut since 2013 by environmental orders from the government of Chile – Barrick said its all-in sustaining costs rose 4.1% in January-March from the same period of 2017 to reach $804 per ounce.

Bullion market prices rose 9.0% year-on-year in Q1 to average $1329.

Barrick’s full-year guidance remains for maximum output of 155 tonnes in 2018, a further 6% drop after 2017’s fall of 4%.

Barrick’s output has now shrunk “nearly 40% since its peak of 2006,” according to Reuters, having sold a raft of assets to raise money in 2014-17.

Total debt has meantime halved to $6.4 billion from the peak of 2012-2013, and “Barrick does not intend to sell further assets for the purposes of debt repayment,” the company said Monday.

“Proceeds from any future portfolio optimization will be used to enhance our project pipeline, or returned to shareholders.”

At the top of gold’s bull run in 2012, ABX paid a dividend of 75 cents per share, offering a yield of some 1.6% to that year’s opening price.

Last year it paid 12 cents per share, a yield on 2017’s opening price of 0.5%.

Chart of Barrick Gold Corporation (NYSE:ABX) vs Dollar price of gold, 1985-2018. Source: BullionVault

Barrick’s stock fell 1.8% on Monday, dropping to 1-week lows.

First quarter results are due from No.4 gold miner Goldcorp (NYSE:GG) on Wednesday, No.2 Newmont (NYSE:NEM) on Thursday, and No.3 Anglogold Ashanti (JSE:ANG) in early May.

Data from the world’s largest gold producer nation China last week said its mining output fell 3% in Q1 after falling 6% across 2017 as a whole.
Gold And Silver Fall Ratio Turns Up As US Bond Yields Rise Near 4 Year High


The GOLD / SILVER RATIO rose from near 2-month lows in London trade on Monday as both metals fell against a rising Dollar after new US data beat analyst forecasts.

With manufacturing activity and sales of existing homes both stronger than Wall Street predicted, world stock markets held flat as falling bond prices saw the yield on 10-year US Treasury debt rise near 4-year highs at 2.98%.

Silver prices erased all of last week’s 2.8% gain by mid-afternoon in London, trading back down at $16.65 as gold fell to 2-week lows of $1323 per ounce.

That pushed up the Gold/Silver Ratio of the two precious metals’ relative prices, with one ounce of gold equal to 79.5 ounces of silver.

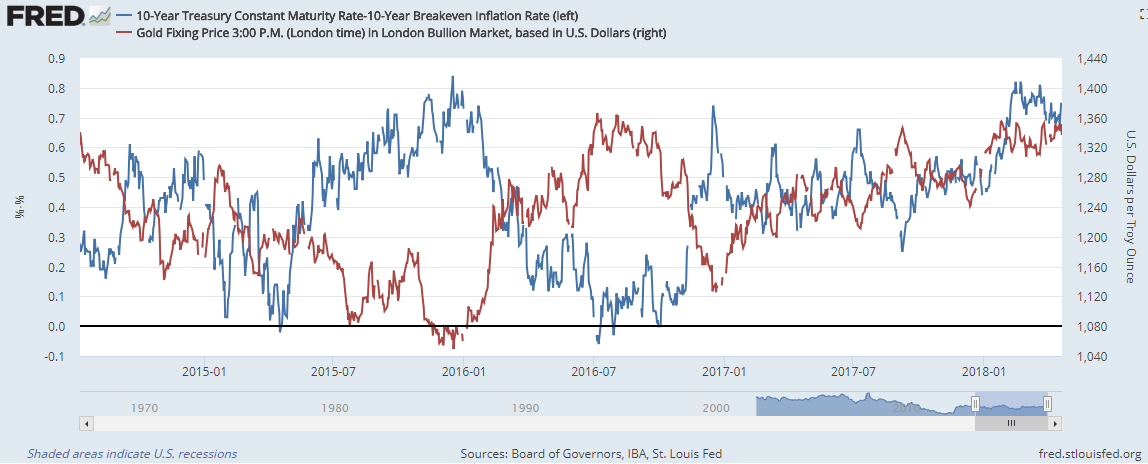
“Higher real [interest] rates have not always resulted in negative gold returns,” says analysis from the mining-backed World Gold Council today, pointing to a “waning” correlation between gold prices and bond yields adjusted for inflation expectations, while “the US Dollar is again [becoming] a stronger indicator of the direction of price.”

Chart of gold priced in Dollars vs. real 10-over-10 US bond yields. Source: St.Louis Fed

Based on monthly returns since 1971, the WGC finds that gold prices have risen twice as much during weak Dollar periods than they fell when the Dollar rose, adding 1.5% on average versus a weaker USD but losing only 0.7% against the greenback when it strengthened.

“Weaker USD and [investors] hedging tail risks [are] supportive, but easing geopolitics [make] price risk broadly balanced,” says a precious metals note from analyst Robin Bhar at French investment and London market-making bank Societe Generale.

“More downside than upside potential,” says the SocGen note of gold, silver and platinum, with palladium “the [only] highlight from a range bound complex – buy the dips.”

Net of bearish bets, the position of hedge funds and other money managers on Comex gold futures and options last week grew to the most bullish since end-March.

Rising to the equivalent of 446 tonnes of notional gold, it was one-eighth greater than the ‘Managed Money’s average net speculative long position of the last 10 years.

Betting on silver prices in contrast stayed negative among money managers for the 10th week running, now the longest stretch since current records began in 2006.

Rising again after falling from 2-year highs when silver prices jumped last week, the Gold/Silver Ratio has risen 81% of the time that silver has fallen on a 1-month basis since 1968.

“Gold failed at resistance [around] $1355 and the 100-day moving average might be the first support level at $1328,” said a brief technical analysis from the trading desk of Belgian refinery group Umicore Monday morning.

Silver “[has] found buyers once again below $17,” says a trading note from Swiss refining and finance group MKS Pamp.

“Gold should find support at the April lows around $1321.”


Disclaimer

This publication is for education purposes only and should not be considered either general of personal advice. It does not consider any particular person’s investment objectives, financial situation or needs. Accordingly, no recommendation (expressed or implied) or other information contained in this report should be acted upon without the appropriateness of that information having regard to those factors. You should assess whether or not the information contained herein is appropriate to your individual financial circumstances and goals before making an investment decision, or seek the help the of a licensed financial adviser. Performance is historical, performance may vary, past performance is not necessarily indicative of future performance. This report was produced in conjunction with ABC Bullion NSW.